

· AFX Research
Production Payments and Net Profits Interests, Explained
Both are carved out of the working interest, both behave unlike a royalty, and a recorded conveyance will not tell you whether either one has been paid out yet.
Table of Contents
A chain shows a conveyance from 1987 creating something called a production payment, and another from 1994 creating a net profits interest. Neither is a royalty, neither behaves like one, and the recorded instruments establish that both exist while saying nothing about whether either is still paying. These are the two carved interests most likely to appear in an older chain and least likely to be read correctly. They sit alongside overriding royalty interests as things taken out of somebody else’s share.
Two carved out interests
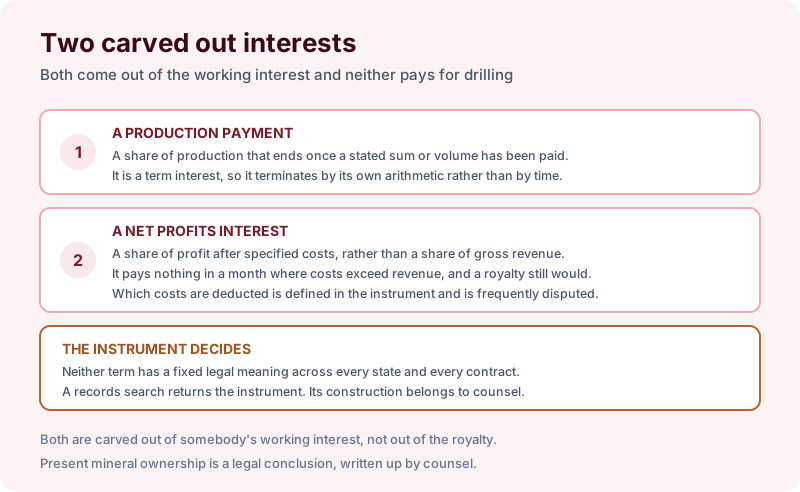
A production payment is a share of production that ends once a stated sum of money or volume of hydrocarbons has been delivered. It is a term interest by arithmetic rather than by calendar, so it terminates when the number is reached and not before.
A net profits interest is a share of profit rather than of gross revenue, calculated after specified costs are deducted. In a month where costs exceed revenue it pays nothing, which an ordinary royalty would not, and which costs may be charged against the account is defined in the instrument and disputed regularly.
Both are carved out of the working interest rather than out of the royalty, so they reduce what the operator and the working interest owners receive rather than what the mineral owner was already getting. Neither carries an obligation to pay for drilling.
Neither term has a single fixed legal meaning across every state and every contract. A records search returns the instrument with its defining language. Construing it is a legal exercise, as set out in a mineral title opinion versus a records search.
Where they appear
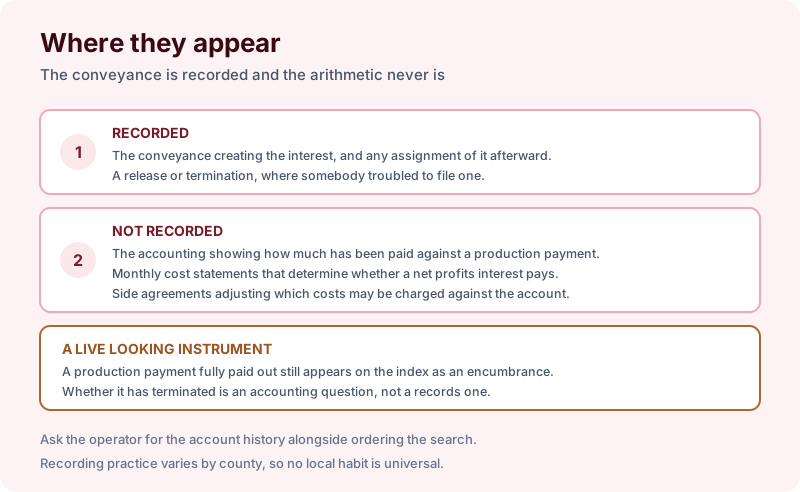
Recorded is the conveyance creating the interest, any assignment of it afterward, and a release or termination where somebody troubled to file one.
Not recorded is everything that determines whether it is still live. The accounting showing how much has been paid against a production payment. The monthly cost statements that decide whether a net profits interest pays anything. Side agreements adjusting which costs may be charged.
So a satisfied production payment still appears on the index as an encumbrance. It was created by a recorded conveyance, it ended by arithmetic, and nothing marks the moment. Whether it has terminated is an accounting question rather than a records one, which is the same shape of problem as in when an oil and gas lease expires.
Why this matters on a purchase
Because a buyer of minerals or of a working interest is buying whatever is left after these come out, and the chain shows the gross rather than the net.
A tract burdened by a 1987 production payment may be entirely unburdened today, or may have fifteen years left to run, and the deed looks identical in both cases. A net profits interest that has never paid because the account has never been in the black is still an interest somebody holds, and a change in prices can make it live again.
The practical step is to ask the operator for the account history at the same time as ordering the search. Recording practice varies by county, so the absence of a recorded release is not evidence either way.
Scoping the search
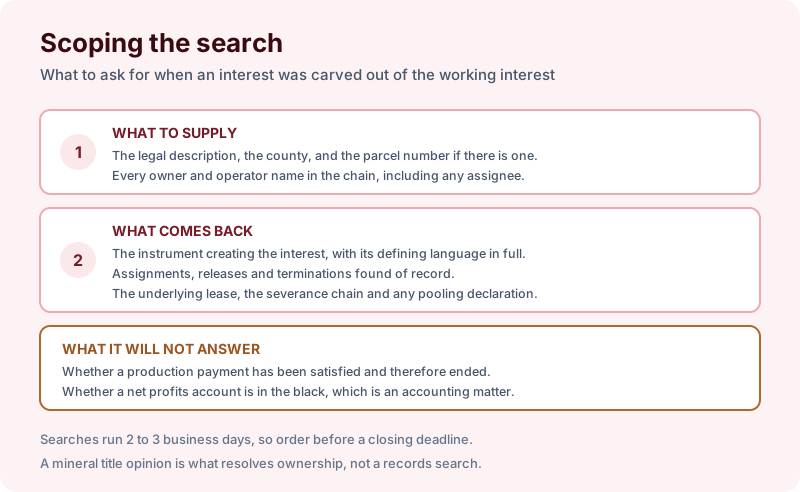
Give us the legal description, the county, the parcel number if there is one, and every owner and operator name in the chain including any assignee. What comes back is the instrument creating the interest with its defining language in full, the assignments, releases and terminations found of record, and the underlying lease, severance chain and any pooling declaration. Our search packages set out the available terms.
What it will not answer is whether a production payment has been satisfied, or whether a net profits account is in the black. Present ownership remains a legal conclusion set out in a mineral title opinion.
The takeaway
Both interests are created by recorded conveyances and extinguished by arithmetic nobody files, which means the record overstates what is outstanding. Get the instrument for the language and the operator for the account. Start the order online, or send us the legal description and the county and we will tell you which term fits and what a search of that scope would and would not cover before anything is ordered.